Credit report check karte waqt agar aapko 5, 8 ya 10 saal purana loan ya credit card account dikh jaye, to naturally question aata hai—“Ye account to kab ka close ho gaya, phir credit report mein abhi bhi kyun hai? Credit report se old account remove kaise hota hai?”
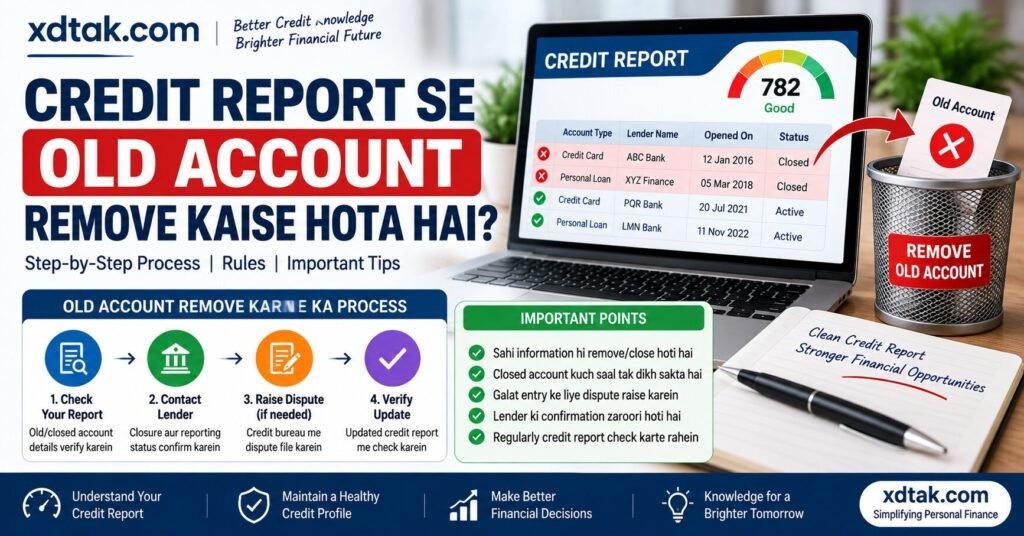
Yahan ek important difference samajhna zaroori hai:
Old account dikhna aur wrong account dikhna, dono alag situations hain.
Agar aapne genuinely koi loan liya tha ya credit card use kiya tha aur wo properly close ho chuka hai, to sirf purana hone ki wajah se us account ko credit report se delete karna generally zaroori nahi hota. CIBIL ke official guidance ke mutabik closed loans ya credit cards credit report mein credit history ke part ke roop mein remain kar sakte hain.
Lekin agar old account mein wrong status, incorrect balance, duplicate account, galat ownership, ya aisa account jo aapka hai hi nahi, to us information ko dispute kiya ja sakta hai.
Is article mein simple Hinglish mein samjhenge ki credit report se old account remove kaise hota hai, closed account ko delete karwana possible hai ya nahi, correction aur deletion mein kya difference hai, aur CIBIL dispute kab raise karna chahiye.
Credit Report Mein Old Account Kyun Dikhai Deta Hai?
Credit report aapki sirf current financial activity nahi dikhati. Isme aapki credit history ke records bhi ho sakte hain.
Isliye agar aapne 2018 mein personal loan liya tha aur 2020 mein fully repay karke close kar diya, to account ka historical record report mein continue reh sakta hai.
CIBIL specifically explain karta hai ki closed loans ya credit cards ka report mein rehna normal ho sakta hai, kyunki wo aapki complete credit history ka part hote hain.
Iska matlab:
Closed account = necessarily error nahi
Aur:
Old account = automatically delete karne layak nahi
Ye distinction bahut important hai.
Kya Closed Credit Card Report Se Remove Ho Jata Hai?
Usually sirf card close karne se historical account entry automatically disappear nahi hoti.
Maan lijiye aapne:
- Credit card liya: 2017
- Card close kiya: 2021
- Outstanding: ₹0
Aap 2026 mein credit report check karte hain aur wahi card closed status ke saath dikh raha hai.
Ye automatically wrong reporting nahi hai.
CIBIL ke current guidance ke mutabik closed accounts credit report mein remain kar sakte hain as part of your financial history.
Lekin agar card closed hone ke baad bhi “Active/Open” show ho raha hai, to correction request karna appropriate ho sakta hai.
Credit Report Se Old Account Kab Remove Ya Correct Karna Chahiye?
Old account ko specifically remove karne ke bajay pehle ye check karein ki information accurate hai ya nahi.
Correction/dispute relevant ho sakta hai agar:
- Account aapka nahi hai
- Same account do baar listed hai
- Closed account “Open” show ho raha hai
- Outstanding balance galat hai
- Payment reflect nahi ho rahi
- Account status incorrect hai
- Credit limit incorrect hai
- Account details mein error hai
CIBIL ke consumer guidance mein duplicate accounts, incorrect account status, incorrect balances/credit limits aur unrecognized accounts jaise examples diye gaye hain.
Yaani objective ye hona chahiye:
“Report mein sirf old account nahi, balki inaccurate information ko correct karna.”
Old Account Aur Wrong Account Mein Difference
Example 1:
Aapne 10 saal pehle ₹3 lakh ka car loan liya tha. Loan fully repay hua aur account “Closed” hai.
→ Ye old account hai, lekin zaroori nahi ki incorrect ho.
Example 2:
Report mein ₹3 lakh ka loan dikh raha hai jo aapne kabhi liya hi nahi.
→ Ye potentially incorrect/unauthorized account hai aur dispute ka strong reason ho sakta hai.
Example 3:
Aapne loan 2023 mein close kar diya, lekin report mein account abhi bhi “Active” dikh raha hai.
→ Ye account-status correction ka matter ho sakta hai.
Credit Report Se Old Account Remove Karne Ka Sahi Process
Agar account genuinely incorrect hai, to aap structured process follow kar sakte hain.
Step 1: Apni Credit Report Carefully Check Karein
Sabse pehle exact account identify karein.
Check karein:
- Lender ka naam
- Account number ke masked/last digits
- Account type
- Opening date
- Closing date
- Current balance
- Payment history
- Account status
- Date reported
Sirf account purana hai is basis par dispute raise na karein. Pehle specific error identify karein.
Step 2: Old Documents Collect Karein
Agar account closed hai, to closure-related proof bahut useful ho sakta hai.
Possible documents:
- Loan closure letter
- No Dues Certificate
- NOC
- Credit card closure confirmation
- Final payment receipt
- Bank statement
- Old credit card statement
- Loan repayment schedule
- Account closure email
Example ke liye, agar aapka personal loan 2021 mein close hua tha, to bank ka closure/NOC document current dispute mein useful evidence ho sakta hai.
Step 3: Concerned Bank Ya NBFC Ko Contact Karein
Agar account kisi particular bank/NBFC se related hai, to pehle unko written complaint dena practical approach hai.
Complaint mein mention karein:
Subject: Incorrect Credit Report Account Information – Correction Request
Details mein:
- Loan/card details
- Closure date
- Current report mein shown status
- Error kya hai
- Correct status kya hona chahiye
- Supporting documents
Written/email complaint ka record future follow-up mein useful hota hai.
Step 4: Credit Bureau Mein Dispute Raise Karein
Agar incorrect information credit report mein still appear kar rahi hai, to relevant credit bureau ke dispute process ka use kiya ja sakta hai.
CIBIL ke current process ke according account-related inaccuracies ke liye online dispute raise kiya ja sakta hai. CIBIL ke instructions mein login karke Credit Reports → Dispute Center → Dispute an Item → Account jaise steps diye gaye hain.
CIBIL ye bhi clearly batata hai ki wo lender ki confirmation ke bina report ke records ko directly modify/delete nahi karta.
Isliye bank/NBFC aur credit bureau dono routes ko samajhna important hai.
Kya CIBIL Old Account Ko Directly Delete Kar Sakta Hai?
Usually sirf aapke request karne se nahi.
CIBIL ke official guidance ke mutabik relevant credit institution ki confirmation ke bina CIBIL reported information ko directly modify ya delete nahi karta.
Simple language mein:
Bank/NBFC reports the information → Credit bureau stores/displays it → Correction usually requires lender confirmation
Isliye agar account genuine hai aur information accurate hai, to “old hai isliye delete karo” type request necessarily accept nahi hoti.
Closed Account Ko Remove Karne Ke Bajay “Closed” Status Correct Karwana
Kai situations mein deletion ki jagah status correction hi correct solution hota hai.
Example:
Report:
Status: Active
Outstanding: ₹0
Lekin aapke paas bank ka closure letter hai.
Aise case mein request ideally ye honi chahiye:
“Please update the account status from Active to Closed.”
Is tarah aap report ko accurate bana rahe hain, historical information ko artificially remove nahi karwa rahe.
Agar Old Account Duplicate Dikh Raha Ho To Kya Karein?
Kabhi-kabhi same loan/card multiple entries mein appear ho sakta hai.
Example:
ABC Bank Personal Loan – ₹0 – Closed
Aur same account:
ABC Bank Personal Loan – ₹0 – Closed
do baar listed hai.
CIBIL duplicate accounts ko report inaccuracies ke examples mein include karta hai.
Aise case mein duplicate entry ko identify karke dispute raise kiya ja sakta hai.
Aapko clearly mention karna chahiye ki:
- Kaunsa account genuine hai
- Kaunsi entry duplicate hai
- Supporting document kya hai
Agar Old Account Aapka Hai Hi Nahi To?
Ye situation more serious hai.
Agar report mein koi old loan ya credit card account hai jo aapne kabhi apply hi nahi kiya, to usse ignore nahi karna chahiye.
Kya Karein?
Pehle lender ka naam aur account details identify karein.
Uske baad:
- Concerned lender se contact karein.
- Account ownership dispute karein.
- Credit bureau mein dispute raise karein.
- Apne other credit accounts aur enquiries bhi check karein.
- Identity misuse ka doubt ho to related financial institutions ko immediately inform karein.
CIBIL bhi unfamiliar accounts aur enquiries ko investigate karne ki advice deta hai.
Credit Report Update Hone Mein Kitna Time Lagta Hai?
Closed account ya corrected data immediately reflect ho, ye zaroori nahi hai.
CIBIL ke FAQ ke according credit institutions data periodically submit karte hain, aur recent closure/pay-off ke baad report mein update reflect hone mein time lag sakta hai. CIBIL currently notes that institutions generally submit data within periodic cycles and a report checked shortly after closure may not yet show the latest status.
Agar account closure ko kaafi time ho chuka hai aur status abhi bhi wrong hai, tab dispute raise karna appropriate ho sakta hai.
Credit Report Dispute Resolve Hone Mein Kitna Time Lag Sakta Hai?
CIBIL ke current FAQ ke mutabik dispute resolution ka turnaround approximately 30 days ho sakta hai, subject to the time taken by the concerned credit institution.
RBI framework ke under credit-information correction complaints ke liye 30 calendar days ka overall resolution framework hai. Eligible delayed cases mein compensation ka framework bhi applicable hai.
Isliye dispute submit karne ke baad complaint number aur reference details save rakhein.
30 Din Se Zyada Delay Ho Jaye To Kya Karein?
Agar qualifying dispute resolution 30 calendar days se beyond chali jaati hai, RBI framework mein ₹100 per calendar day compensation ka provision hai.
Example:
Suppose qualifying dispute ko resolve hone mein 34 calendar days lag gaye.
Potential delay:
34 − 30 = 4 days
Potential compensation:
4 × ₹100 = ₹400
Lekin compensation ki actual eligibility, delay kis entity ki responsibility hai aur case ke applicable facts matter karte hain. Isliye har old-account dispute automatically compensation case nahi ban jata.
Kya Old Account Delete Karne Se CIBIL Score Improve Hoga?
Automatically nahi.
Actually, agar old account accurately reported hai, to usko remove karne ka objective hi questionable ho sakta hai.
Agar account mein wrong overdue, wrong balance ya incorrect status hai, to accurate correction important hai.
Score ka change multiple factors par depend karega, including overall repayment history, credit utilization aur other credit information.
Isliye “old account delete = score instantly improve” ek unreliable claim hai.
Kya Closed Account Credit Score Ke Liye Bura Hota Hai?
Not necessarily.
Closed account ka report mein rehna apne aap mein negative error nahi hai. CIBIL specifically closed loans/cards ko complete credit history ka part batata hai.
Important ye hai ki:
- Account status correct ho
- Balance correct ho
- Payment history accurate ho
- Ownership correct ho
Agar ye details accurate hain, to account sirf purana hone ki wajah se problematic nahi maana jana chahiye.
Credit Report Se Old Account Remove Karne Ke Naam Par Fraud Se Bachna
Online aapko aise claims mil sakte hain:
“₹999 mein old CIBIL account delete.”
“Guaranteed CIBIL cleanup.”
“Score 100 points increase guarantee.”
Aise claims se cautious rahen.
Credit bureau reporting ko manipulate karne ke liye kisi unauthorized agent ko personal banking credentials, OTP, CVV, internet-banking password ya sensitive identity documents unnecessarily share na karein.
Official lender aur bureau grievance/dispute channels ko preference dein.
Credit Report Correction Ke Liye Documents Kaise Prepare Karein?
Dispute file karte waqt documents organized rakhna useful hai.
Example Document Set
Document 1: Loan closure letter
Document 2: Final payment receipt
Document 3: Bank statement showing final repayment
Document 4: Credit report page showing incorrect status
Document 5: Bank complaint acknowledgement
Isse aapke claim ko explain karna easier hota hai.
CIBIL ke dispute portal mein supported file formats aur attachment requirements bhi provided hain; current portal guidance ke mutabik documents such as PNG/JPG/JPEG/PDF accepted ho sakte hain, with specified upload limits.
Exact upload requirements time ke saath change ho sakti hain.
Credit Report Check Karne Ki Practical Checklist
Har baar credit report download karne par sirf score mat dekhein.
Ye checklist follow karein:
Personal Information
Naam, DOB aur contact details verify karein.
Accounts
Active aur closed loans/cards check karein.
Payment History
Late payment, overdue ya missed-payment entries check karein.
Balance
Closed account ka outstanding incorrectly positive to nahi dikh raha?
Account Status
Closed account “Open/Active” to nahi?
Duplicate Accounts
Same loan/card multiple times to listed nahi?
Enquiries
Unknown lender enquiries to nahi?
Regular checking se errors ko early identify karna easier ho sakta hai. CIBIL bhi consumers ko report monitor karne aur inaccuracies ko dispute karne ki guidance deta hai.
Credit Report Se Old Account Remove Karne Ke Baad Kya Check Karein?
Dispute resolve hone ke baad fresh report/check karna important hai.
Ye verify karein:
- Account status correct hai
- Balance ₹0 ya actual amount ke according correct hai
- Closing date correct hai
- Payment history corrected hai
- Duplicate entry remove/correct hui hai
- “Under Dispute” marker appropriately removed hua hai
CIBIL ke current FAQ ke mutabik, bank/credit institution se corrected data receive hone ke baad CIBIL records update karta hai.
Frequently Asked Questions
Credit report se old account remove kaise hota hai?
Agar account genuine hai aur correctly reported hai, to sirf old hone ki wajah se usse delete karna generally necessary nahi hota. Agar account mein incorrect status, balance, ownership ya duplicate entry hai, to lender aur relevant credit bureau ke dispute process se correction request ki ja sakti hai.
Kya closed loan credit report mein dikhna normal hai?
Haan. Closed loan ka historical record credit report mein remain kar sakta hai. CIBIL closed loans aur credit cards ko complete credit history ka part batata hai.
Kya CIBIL closed account delete kar sakta hai?
Sirf customer ke request par accurate account ko directly delete karna generally possible nahi hota. CIBIL ke according information modification/deletion ke liye concerned Credit Institution ki confirmation required hoti hai.
Credit report mein old account Active show ho raha hai, kya karein?
Concerned bank/NBFC ko closure proof ke saath written correction request dein. Saath hi relevant credit bureau mein account-status dispute raise kiya ja sakta hai.
Duplicate old account ko kaise remove karein?
Agar same loan/card report mein multiple times listed hai, to duplicate account dispute raise karein aur relevant account details/supporting documents provide karein. CIBIL duplicate accounts ko report inaccuracies ke example ke roop mein identify karta hai.
Old account remove hone se CIBIL score badh jayega?
Guaranteed nahi. Accurate information correct hone se report improve ho sakti hai, lekin score ka exact effect overall credit history aur scoring model par depend karta hai.
Credit report correction mein kitna time lagta hai?
CIBIL ke current FAQ ke according dispute resolution ka turnaround approximately 30 days ho sakta hai, subject to the concerned credit institution.
30 din se zyada dispute pending rahe to compensation mil sakta hai?
Eligible delayed cases mein RBI framework ke under ₹100 per calendar day compensation ka provision hai after the applicable 30-day resolution period.
Also Read :-
- Credit Card Close Karne Se Credit Score Kitna Affect Hota Hai?
- Credit Report Mein Unknown Loan Dikhe To Kya Karein?
- Credit Report Mein Late Payment Galat Show Ho To Kaise Correct Karein?
Conclusion
Credit report se old account remove kaise hota hai iska sabse important answer ye hai ki har old account ko delete karna zaroori ya possible nahi hota.
Agar loan ya credit card genuinely aapka tha, properly close ho chuka hai aur report mein accurately “Closed” show ho raha hai, to uska historical record credit report mein rehna normal ho sakta hai. CIBIL ke according closed accounts complete credit history ka part ho sakte hain.
Lekin agar old account ke saath incorrect balance, wrong account status, duplicate entry, wrong payment history ya ownership error hai, to correction request raise karni chahiye.
Practical process simple hai:
Credit report check karein → error identify karein → proof collect karein → lender ko complaint dein → credit bureau mein dispute raise karein → resolution track karein → updated report verify karein.
Sabse important baat: kisi third-party agent ke “guaranteed CIBIL cleanup” claims par depend karne ke bajay official bank/NBFC aur credit bureau dispute channels use karein.
Credit reporting practices, dispute timelines aur applicable rules update ho sakte hain. Isliye specific case mein concerned lender, credit bureau aur RBI ki latest official guidance ko priority dein.